If all you want is to receive and send coins, an exchange account is simply an address book that can take deliveries and keep a record of them.
On-chain transfers need no platform at all: if you have an address, you can send. But sooner or later you run into a few things the chain can't settle by itself — how money turns into coins, how coins turn back into money, why the USDT a friend sent you is sitting on a different chain, and whether the transfer you just made actually arrived. Those answers now live mostly inside an exchange account, which is why the account comes first.
This guide runs in four parts: gathering what you need, signing up and verifying your identity, three security switches, and getting your first deposit address. The parts to take care over are the security switches and one rule: the address follows the network.
- Pickup: gather your materials
An email address or phone number you actually use, your original ID document, an authenticator app, and a sheet of paper. - Sorting: sign up and verify your identity
Signing up takes a few minutes; verification usually comes back within 48 hours. - Reinforcement: three security switches
Two-factor authentication, anti-phishing code, withdrawal whitelist — flip all three before any money moves. - Signature: your first deposit address
Pick the coin, pick the network, get the address, then take delivery of the first transfer.
It starts with a USDT transfer that got stuck
A friend wants to send you some USDT. What he's holding happens to be on BNB Smart Chain, while the place you need to pay only takes Tron. And once that money is no longer needed, you'd like to turn it back into currency you can spend. Three things — and your wallet can't do a single one of them. It only moves coins that already exist: it doesn't switch chains, it doesn't convert to fiat, and it won't tell you which leg of the journey the money is on right now. The exact spot where this delivery gets stuck is where the three gaps sit when you have no exchange account, and none of the three is the kind of gap you can get around by paying a bit more in fees.
First, the fiat doorway. You're holding cash and want USDT, or holding USDT and want money you can actually spend — the chain has no native way to do either, because a chain only moves coins that already exist. What an exchange account provides is precisely that way in and out.
Second, swapping coins and swapping chains. Your friend is sending USDT on BNB Smart Chain; the party you need to pay only accepts USDT on Tron. Handling that purely on-chain means finding a bridge yourself, paying fees at both ends, and judging whether the tool itself can be trusted. With an account it's simpler: deposit on the original network, withdraw on the target network, and in between it's just one internal bookkeeping entry at the platform. Swapping one coin for another works the same way.
Third, the checking itself. A wallet can receive coins too, but it won't tell you the minimum deposit on this network, how many confirmations count as done, or which leg the money is stuck on. An exchange's deposit page and deposit history put all of that out in the open, and the first time you receive coins you can't do without those few lines of text. Whether to leave coins on a platform long-term or move them into your own wallet is a separate question — this guide spreads out the risks on both sides, and there's no hurry to choose now.
What you need before signing up for Binance
Most people who stall on sign-up stall because they did it in the wrong order: they open the page and only then discover the authenticator isn't installed and the ID is in another bag. Have these ready in advance and the whole thing goes through in one sitting.
- Confirmation that Binance serves your country. Some countries and regions aren't covered; the sign-up page will tell you.
- An email address or phone number you'll be keeping. It's how you'll recover the account and receive security alerts later, so no throwaway addresses and no numbers you're about to cancel. Ideally that mailbox has two-step verification switched on as well.
- Your original ID document. Verification asks for photos, and what you photograph has to be the document itself — not a photocopy, not a picture on a screen. While you're at it, check that it hasn't expired.
- An authenticator app. Install it beforehand so it's ready the moment you finish signing up. Installing it in a rush after a withdrawal has already been blocked makes for a bad evening.
- A sheet of paper and a pen. For copying down two strings: the authenticator's backup key, and the password you thought up for this account alone. On paper — no screenshots, nothing sent through a chat app.
One more word about your surroundings: do the whole thing on your own device, not a public computer, and don't follow a link somebody hands you. Reach the sign-up page from the official site or the official app store, and leave the ad slots in search results alone.
Where the Referrer ID field is, and whether a typo can be fixed
The flow itself is short. Only two points are worth pausing at, and they're marked below.
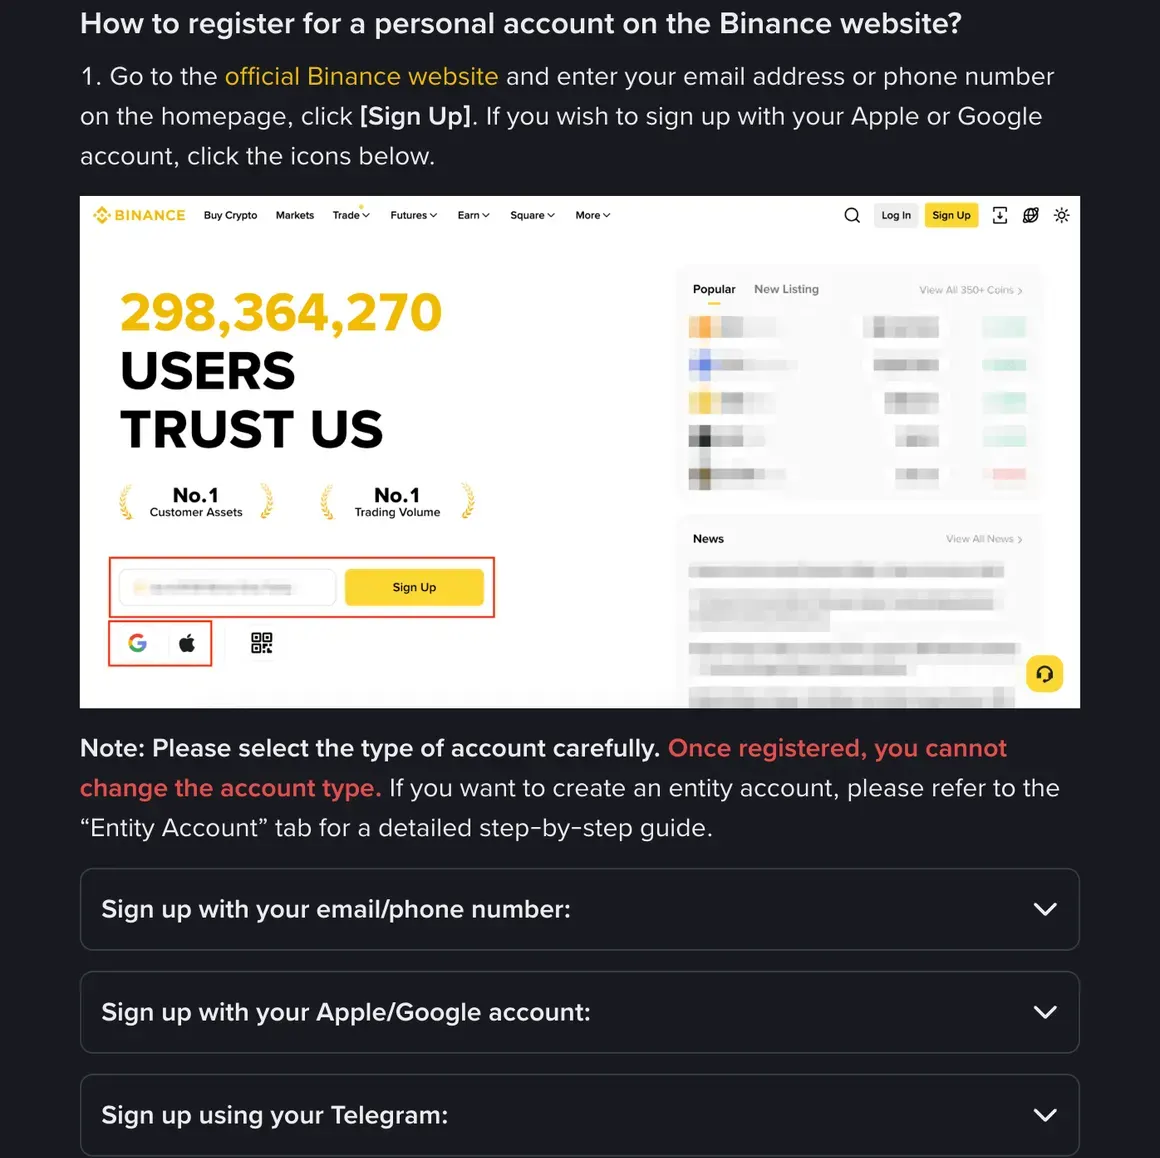
- Open the sign-up page. Use the official site or the official app, and read the domain before you type a password.
- Choose how you sign up. Email or phone number are the usual options, and the page may offer other login methods too — go by what's shown at the time. Think up a password for this account alone; don't reuse your email password or one from another exchange.
- Take the code and finish verification. Email codes love the spam folder, so look there first. If the SMS is slow, wait a full minute or two before hitting resend — tapping it repeatedly is a good way to get rate-limited.
- Enter the referral code. This field goes by several names: Referrer ID, referral code, Referral ID. Sometimes it's folded away under "optional" and you have to expand it before it's visible. Enter BN3233. Sign-up is the easy place to enter it; new accounts that missed it can bind within 30 days if eligible, but a wrong code that binds can't be changed. Copy it from here, paste it in and check the characters.
- Submit and go into the account. It's empty at this point, and moving money into it comes last — after the next two sections are done.
Where to sign up and enter the code
In that field on the sign-up page, enter BN3233 — up to 20% back on trading fees (actual rate per Binance's current Affiliate terms and your own account page). If you sign up with our referral code, trading on that account may earn us a referral fee, at no extra cost to you.
Open the sign-up page yourself from the official Binance site or app, and enter the code BN3233 in the referral field.
Register on Binance with BN3233 Run through the checklist before your first depositThis is an independent third-party site, not an official Binance website. On-chain transactions are irreversible — proceed carefully and take responsibility for your own risk.
On fees, to put it precisely: signing up with a referral code gets you up to 20% back on trading fees. "Up to" is doing real work in that sentence — the actual rate, the product lines it applies to and how long the offer runs can all change, so go by Binance's current Affiliate terms and what your own account page shows. Don't read it as twenty per cent off every trade. If you mainly send and receive USDT, there's something more concrete: the fees saved by picking the right network for a single transfer are often worth more than the fee discount, and the fee comparison guide puts the numbers side by side.
Six reasons Binance sends your verification back
Verification (KYC) is a regulatory requirement in this business, nearly every function sits behind it, and there's no getting past it. The flow is usually three parts: fill in your basic details → photograph the front and back of your ID → a liveness face check. Binance's Help Center says reviews are usually done within 48 hours; don't keep resubmitting while you wait.
The reasons for rejection are heavily concentrated, and knowing them in advance saves you a round trip:
- Glare and blur. A laminated document throws a white patch under a lamp; move the light away, or change the angle and shoot again.
- Corners cut off. All four corners have to be in the frame, with a margin of space around the document. Don't crop it to the edges.
- It isn't the original. Photocopies, scans, photos taken off a screen — the system generally recognises all of them.
- The details don't match. The name, date of birth and document number you type must be exactly as they appear on the document, without rewording a single character.
- The document has expired. Nothing the platform can do about this one; you'll have to renew it first.
- Poor conditions for the liveness check. Backlight, a hat or sunglasses, your face not inside the frame — any of these can fail. Find a white wall, get the light onto your face, then run it.
A rejection doesn't mean there's something wrong with the account; reshoot as instructed and submit again. How the verification tiers are divided and what each tier can be used for is something the platform adjusts, so go by what your account page shows at the time — old guides floating around online go stale on this item faster than on anything else.
Before any money comes in: 2FA, the anti-phishing code and the whitelist
The order matters: do these three before any money comes in, rather than going back to them once the account already holds funds.
Two-factor authentication (2FA)
Go into account security settings and bind an authenticator app: scan the code, enter one rotating code to complete the binding, then copy the backup key onto paper. Its whole purpose is to let you restore the authenticator after the phone is lost or the app deleted by accident, and keeping it only inside that phone is the same as not keeping it. Once it's bound, both login and withdrawal ask for a six-digit code. Those few seconds are what closes off the most common route of all: password leaked, account gone.
The anti-phishing code
Treat it as a seal the two of you agreed on in advance: you set a custom string in security settings, and from then on every official email carries it; in some countries, official SMS messages do too. A letter "from Binance" without that seal can be treated as fake no matter how convincing the layout. Don't use your birthday or your account name; any combination you'll recognise will do.
The withdrawal whitelist: only send to addresses you registered
The whitelist means withdrawals are only allowed to addresses you registered in advance. It's the saved-addresses book from online shopping: fifteen extra seconds to register an address once, and after that no parcel ever goes to a stranger's door. Turned around: if someone does get into the account, they can't write a waybill straight to an unfamiliar door — they'd first have to add a new address to the book, and with the whitelist safety restriction switched on, a new address has to wait before it works. It shrinks the damage; it doesn't make a break-in harmless.
Two points about using it. The moment you register an address is the moment to check it properly: the whitelist only guarantees that everything goes to this address from now on — it doesn't judge whether the address is right, and registering a wrong one just makes the mistake permanent. A newly added address usually has a waiting period before it takes effect; don't resent the delay — on the day something really does go wrong, that wait is the window in which you notice.
One thing to know in advance: after a fresh sign-up, a password change, or a login from a new device, platforms often add a temporary withdrawal restriction — commonly anywhere from 24 to 48 hours, with the page as the authority. So don't change your password on a day you're planning to withdraw. The risk-control guide has a fuller list of the ways that button goes grey.
Your first deposit address: change the chain and it's a different house number
Once the account is open, the thing that genuinely belongs to you is that string of characters on the deposit page. The route to it: Assets → Deposit → choose crypto → choose the coin → choose the network, and only then do the address and QR code appear.
Watch the order of those last two steps: the address is decided by the coin-and-network pair together, not one fixed address per coin. The same USDT gives you two entirely unrelated strings on Tron and on Ethereum; if the sender used chain A and you handed over an address on chain B, that money will not find its own way back.
| What you're receiving | Common network | What the address looks like | Memo needed? |
|---|---|---|---|
| USDT | TRC20 (Tron) | Starts with T | No |
| USDT | ERC20 (Ethereum) / BEP20 (BNB Chain) | Both start with 0x | No |
| BTC | Bitcoin mainnet | Starts with 1 / 3 / bc1 | No |
| XRP, TON and the like | Their own mainnets | Each chain's own format | Yes — leave it out and it gets stuck |
The dangerous one is the second row: ERC20 and BEP20 addresses look exactly alike, both starting with 0x, indistinguishable by eye and hard for the system to catch on your behalf. This box can only be settled by both ends agreeing out loud — whichever chain you picked on the deposit page is the one the sender has to pick. If you're unsure, read the network guide, or answer two questions in the Network Picker and get the answer straight away. Whether a wrong choice can still be rescued is set out case by case in this guide, and the best version of it is the one you never need.
Once you have the address, two lines of small print are worth reading. The minimum deposit — deposits below the threshold are commonly neither shown nor returned, with the details in the minimum deposit guide. And Memo / Tag — when you're receiving XRP, TON and similar coins, that extension number beside the address has to go to the sender together with it, and the Memo guide covers what to do when it's been left out.
One more habit that costs nothing: go back into the deposit page and copy the address fresh before every deposit, rather than using an old one saved in a chat log. Addresses stay valid long-term most of the time, but some networks update them during system upgrades, and "most of the time" isn't worth betting your principal on. The full walkthrough is in the deposit guide.
When the first transfer doesn't show up, check in this order
When somebody shouts that the money hasn't arrived, the money is usually sitting perfectly safely on the chain or in the account — it just isn't on the page they happen to be looking at. Work through the order below and you can pin down which leg it's on.
- First, work out which tab you're looking at. Coins deposited from the chain sit in the Spot Account. P2P works the same way now: since 29 September 2026, anyone who only places orders and hasn't posted ads uses the Spot Account by default, while advertisers stay on the Funding Account for the time being (Binance's migration FAQ, read October 2026). Searching the coin name from the assets overview is far quicker than flipping through tabs one at a time. How to move funds between accounts is in the transfer-versus-withdrawal guide.
- Ask the sender for the TxID. No TxID means the money never actually made it onto the chain — it may still be stuck in the other platform's review, and checking a block explorer at that point is wasted effort.
- With a TxID, go and look on-chain. Take it to the block explorer for that network and check the status and the confirmation count; the tracking guide shows you which fields to read.
- On-chain says success but the account still shows nothing? Most likely the confirmations haven't yet reached the platform's threshold. "Successful on-chain" and "credited" are two separate lines, and the arrival-time guide makes the difference between them clear.
- Confirmations are there and it's still missing? Check those three things. Whether the amount was below the minimum deposit, whether the Memo that should have been filled in was filled in, and whether that network happens to be under maintenance. The not-arrived checklist sets out the full order; if you reach the end without an answer, take the TxID to support — giving them everything at once works better than chasing repeatedly.
The one urge to resist through all of this is sending it again: transferring a second time because you can't see the first only turns one set of books to reconcile into two. The easier route is further upstream — for any new address, send a small amount first to test the route, and the test transfer guide explains why this plodding method is what experienced hands agree on.
Frequently asked questions
Can I get a deposit address before my verification is approved?
No. A newly registered Binance account can't deposit or trade until verification is complete; finish verification first and the deposit page will give you an address.
I mistyped one character of the referral code. Is it too late to fix?
It is never too late before you submit, which is why that checking glance belongs before you press submit, not after. The field goes by several names — Referrer ID, referral code, Referral ID — and is sometimes folded away under an optional section you have to expand before you can see it. What goes in it is BN3233. After you submit it is a different story: once a referral link is in place it can't be changed or removed, so a wrong code that binds stays bound. If you left the field empty, a new account can still bind a code from the Referral page within 30 days of sign-up, as long as it has no deposits or trades yet, has no existing referral link and meets the other conditions. The trading fee cashback is up to 20%; the actual rate and which product lines it covers go by Binance's current terms and what your account page shows.
How long after opening the account until I get a deposit address?
Once verification passes, go to the deposit page, choose the coin and the network, and the address appears — usually instantly. The thing to remember is that the address follows the network: switch to another network and you have to fetch a new address, because the one from the previous chain will not do.
Why is the withdrawal button unclickable on a brand-new account?
After a fresh sign-up, a recent password change, or a login from a new device, platforms often add a temporary withdrawal restriction — commonly anywhere from 24 to 48 hours, with the page as the authority. This is not a problem with your account; it lifts once the restriction period passes. The various ways that button goes grey are covered in the risk-control guide.